
Health Insurance For Sole Proprietors: Key Coverage Options And Plan Types Explained

Plan Types and Coverage Categories for Sole Proprietors
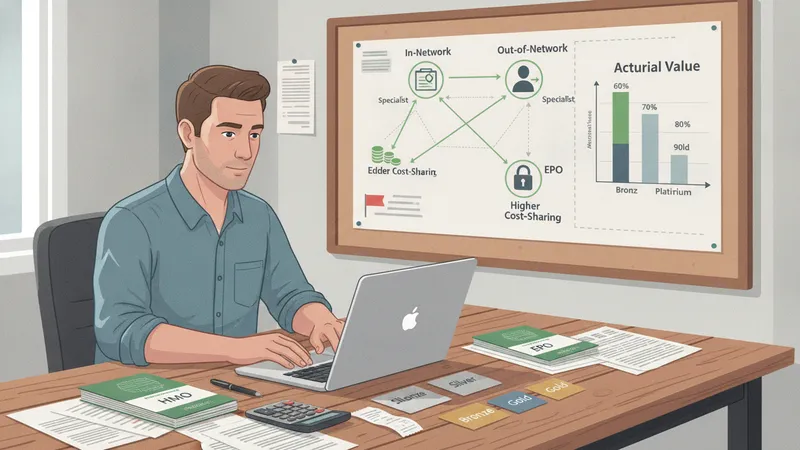
Managed care models represent the most common broad categories and can shape both access and cost-sharing. Health maintenance organization (HMO) models typically require members to select a primary care clinician to coordinate care and provide referrals for specialists; these plans can restrict out-of-network benefits. Preferred provider organization (PPO) designs often allow direct access to specialists and out-of-network providers but may impose higher cost-sharing for those choices. Exclusive provider organization (EPO) plans generally require use of an in-network provider list with fewer or no out-of-network benefits. Each category may be offered in multiple cost-sharing tiers.
Individual market plans sold through public exchanges or directly by insurers commonly come in metal tiers or alternative structures reflecting different actuarial values. Tiers usually indicate the percentage of expected costs the plan covers versus the enrollee’s share, which can help sole proprietors estimate typical annual expense under routine and higher-use scenarios. Some markets also offer catastrophic or limited-duration options subject to eligibility and regulatory conditions; these options often have different coverage rules and may restrict certain benefits, especially for routine care.
Association plans, professional group arrangements, or association health arrangements are sometimes available to independent workers through trade or professional organizations. These models can provide a grouping mechanism to negotiate terms, but regulatory frameworks vary by jurisdiction and may affect consumer protections and coverage guarantees. When considering such arrangements, sole proprietors may review the legal structure, whether coverage is fully insured or self-funded, and the protections that apply under relevant consumer protection laws.
Supplemental and ancillary coverage may include dental, vision, short-term disability, or critical illness riders that can be added to primary medical coverage or purchased separately. These options may address gaps in routine care access or income protection during temporary disability but can add to monthly cost. Sole proprietors often consider whether separate savings mechanisms or tailored ancillary products better match their anticipated needs versus bundled add-ons, keeping in mind differences in exclusions, waiting periods, and claim processes.