
Secured Business Credit Cards: Building Business Credit With A Security Deposit

Factors to consider when selecting a secured business credit card with a refundable deposit
Key factors include the issuer’s reporting practices, deposit-to-limit methodology, fee schedule, and refund terms. Confirming whether the issuer reports to commercial credit bureaus or consumer bureaus can clarify how the account may affect business credit records. Fee structures—such as annual fees, transaction fees, and penalties—should be reviewed alongside interest rate terms for carried balances. Refund timing and conditions for the deposit, including any holds or offsets for outstanding balances, are practical considerations that can affect liquidity planning for small enterprises.
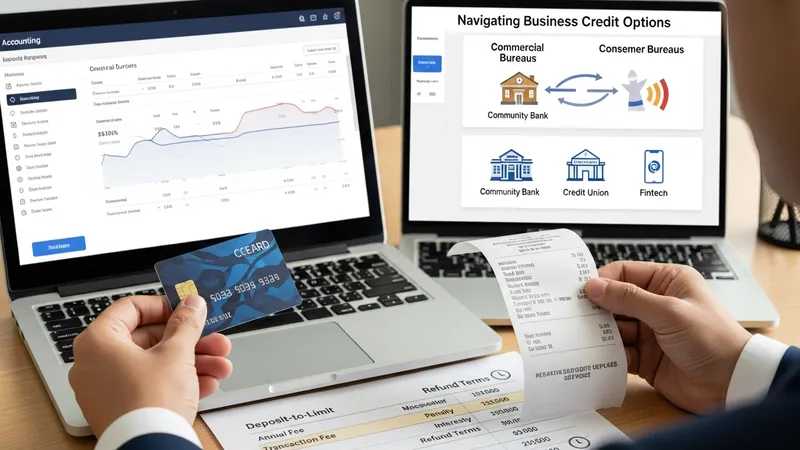
Provider type can influence account features and underwriting approaches. Community banks and credit unions may emphasize local relationships and offer conservative underwriting, while fintech providers may prioritize digital onboarding and integration with accounting tools. Each provider category may differ in documentation requirements and the speed of decisions. Businesses often weigh administrative convenience and reporting characteristics when comparing offers, rather than focusing on a single attribute.
Scalability and long-term product pathways matter for businesses expecting growth. Some secured accounts may explicitly offer a path to unsecured products or periodic reviews that could lead to limit adjustments; others may remain deposit-backed for extended periods. Considering whether an issuer provides options for future transitions or additional business credit products may align account selection with broader financial planning. These are potential outcomes, not guarantees, and vary by issuer and business performance.
Finally, transparent disclosures and accessible customer support can ease account management. Reviewing account agreements for precise language about deposits, refunds, reporting, and dispute processes helps set expectations. Asking about typical timelines for deposit refunds and the mechanics of reporting—phrased as information requests rather than requests to act—can provide clarity. Gathering these details supports informed decision-making about whether a particular deposit-backed card aligns with a business’s documentation and credit-building objectives.